One of the most common questions we hear from homeowners is surprisingly simple: “Why is my house insured for more than I think it’s worth?”
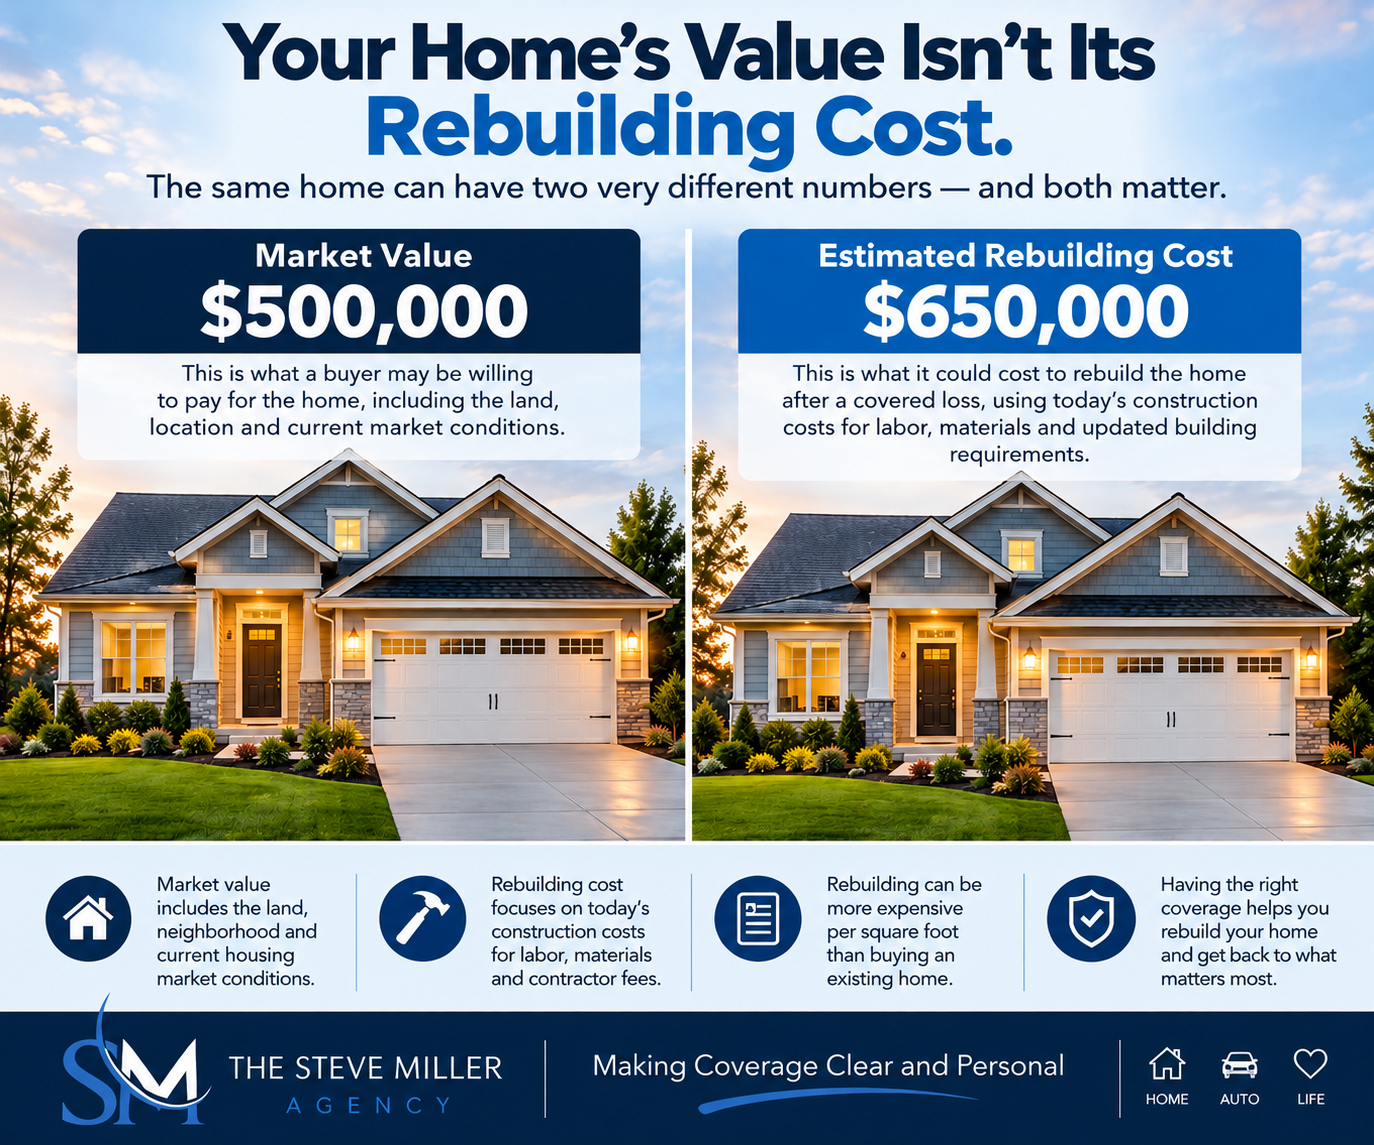
It’s a great question—and the answer comes down to an important distinction between market value and replacement cost.
Market Value Isn’t the Same as Replacement Cost
Your home’s market value is essentially what someone may be willing to pay for the property. It can be influenced by the neighborhood, school district, acreage, interest rates, housing demand and even the specific street where you live.
Homeowners insurance looks at your home differently.
The goal is generally to determine what it could cost to rebuild the home after a covered loss, using today’s construction costs.
That means accounting for things like labor, materials, roofing, flooring, cabinetry, electrical systems, plumbing, debris removal and many of the other expenses involved in rebuilding a home.
Those two numbers can be very different.
Why Rebuilding Can Be More Expensive
Imagine purchasing a home for $500,000. Part of that purchase price represents the land underneath the home—which doesn’t need to be rebuilt after a fire.
At the same time, rebuilding an existing home from the ground up can sometimes be considerably more expensive per square foot than purchasing an existing home.
If a major loss occurs, you’re also not building under ideal circumstances. Materials may need to be ordered quickly, contractors need to be coordinated, damaged materials removed, and the new home reconstructed to current requirements.
That’s why simply using your purchase price or a Zillow estimate isn’t necessarily a good way to determine how much homeowners insurance you need.
Details Matter
When we’re helping homeowners throughout Dayton, West Chester and Southwest Ohio, some of the details that can significantly affect replacement cost include:
• Finished square footage
• Number of stories
• Basement size and finish
• Roofing material
• Exterior construction
• Hardwood and specialty flooring
• Custom cabinetry and countertops
• Bathrooms and kitchens
• Attached structures
• Recent additions or renovations
This is also why we believe homeowners insurance shouldn’t be treated like a commodity where the only goal is finding the lowest premium. The coverage has to work when you actually need it.
When Should You Review Your Home’s Coverage?
A good time to review your homeowners insurance is after making a significant improvement to your property.
Finished the basement? Remodeled the kitchen? Added a room? Built an outdoor living space? Installed higher-end finishes?
Those changes can affect what it would cost to rebuild your home.
Even if you haven’t renovated recently, periodically reviewing your replacement cost with your insurance agency can make sense as construction and labor costs change.
Our Approach
At The Steve Miller Agency, we want our customers to understand what they’re buying—not simply receive an insurance quote.
When we evaluate homeowners insurance, replacement cost is an important part of that conversation. We want to understand the home, explain the coverage and help customers make an informed decision about protecting it.
If you’re purchasing a home or haven’t reviewed your homeowners coverage recently, we’d be happy to take a second look.
The Steve Miller Agency
Serving Dayton, West Chester and communities throughout Ohio


Leave a Reply